
Even after your vehicle undergoes perfect repairs following an accident, its market value often drops permanently. This loss belongs to you, not the at-fault driver. In fact, diminished value coverage is available in all 50 states, yet most policyholders remain unaware of this financial recovery opportunity. According to industry data, insurers frequently undervalue property damage claims, leaving significant compensation on the table for vehicle owners who do not have expert support. This guide explains how to quantify that loss and recover it through verified comparable sales and defensible appraisal clauses.
What Is Diminished Value?
Diminished value is the difference between the pre-accident market value of your vehicle and its post-repair market value. It is a real-world financial loss that occurs because potential buyers perceive a vehicle with an accident history as less desirable, regardless of how well it was repaired. This concept is critical for anyone seeking full indemnification after a collision. (Frequently Asked Questions Vehicle)
Most insurance carriers rely on proprietary algorithms that often ignore these market realities. They may offer a settlement based solely on repair costs or a generic book value. However, inherent diminished value is a distinct category of loss that requires professional analysis to prove. Without a certified valuation document, you are likely accepting a settlement that is significantly lower than what your vehicle is actually worth in the current market.
Types of Diminished Value Claims
Understanding the specific type of diminished value applicable to your situation is the first step in recovery. There are three primary categories recognized in the industry:
Inherent Diminished Value
Inherent diminished value is the most common and significant form of loss. It exists solely because your vehicle has an accident history on its title or vehicle history report. Even if the repairs are flawless, the stigma of the accident record reduces the vehicle's resale price. This type of loss is recoverable in most states, provided you can demonstrate the market impact through verified data.
Repair-Related Diminished Value
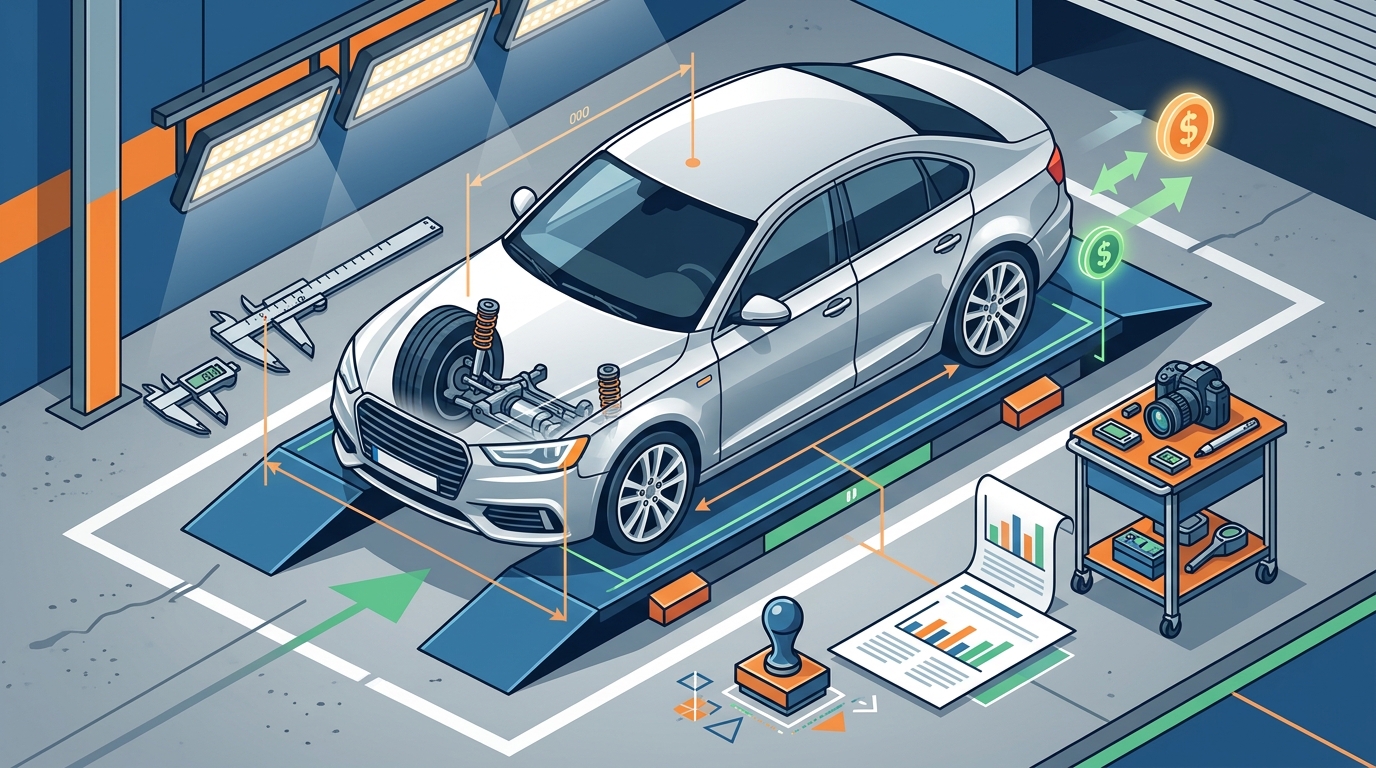
This type of loss occurs when the repairs themselves were not performed to manufacturer standards or used non-OEM parts that affect performance and safety. If the quality of the repair work is subpar, the vehicle's value drops further than it would from the accident history alone. This requires a detailed reparability analysis to identify specific defects or deviations from factory specifications.
Derivative Diminished Value
Derivative diminished value refers to losses resulting from secondary damage that was not immediately apparent at the time of the accident. For example, if an accident causes stress fractures in the frame that only manifest months later, the resulting loss in value is considered derivative. This type of claim is more complex and often requires extended monitoring and professional diagnostic support.
How Diminished Value Is Calculated
Calculating diminished value is not a guesswork exercise. It relies on a defensible deviation-percentage formula applied to verified comparable sales. The process involves several rigorous steps to ensure accuracy and acceptance by insurance carriers.
Step 1: Establishing Pre-Loss Actual Cash Value
The first step is determining the true pre-loss Actual Cash Value (ACV) of your vehicle. This is not the price you paid for the car, but its fair market value immediately before the accident. This figure serves as the baseline for all subsequent calculations. A complete appraisal establishes this value using real-time market data, ensuring it reflects the specific condition, mileage, and options of your vehicle.
Step 2: Analyzing Verified Comparable Sales
Real comparable sales are the cornerstone of any diminished value report. We analyze recent sales of similar vehicles with accident histories to determine the market discount. This data is far more accurate than generic estimates or book values. By examining actual transaction prices, we can quantify exactly how much the market penalizes your specific make, model, and year for having an accident history.
Step 3: Applying the Deviation Formula
Once the baseline value and comparable sales data are established, a standardized formula is applied to calculate the specific dollar amount of the loss. This formula accounts for factors such as vehicle age, mileage, and the severity of the damage. The result is a precise, defensible number that you can use in negotiations or appraisal clauses.
Support for Personal Injury Law Firms
For personal injury law firms, vehicle property damage is often a neglected aspect of the overall claim. Most firms focus on bodily injury while leaving clients to handle the vehicle portion alone. This results in missed compensation, client frustration, and extra work for legal teams. A dedicated valuation partner ensures every client receives accurate and complete compensation.
The Opportunity for PI Firms
Every accident includes a property damage claim, yet most firms lack a system to manage them efficiently. Accident volume and total loss frequency create a major opportunity for firms to deliver more value to clients. We seldom see insurance total loss proposed settlements valued properly. This demonstrates how often insurers undervalue vehicles and how much value is left on the table without expert support.
Bulk Solutions for High-Volume Firms
Our bulk solutions are designed for teams that handle multiple motor-vehicle personal-injury cases each month. The WHO OWES WHAT Portal centralizes all property damage work so your team can manage dozens or even hundreds of files with ease. It simplifies communication, improves consistency, and saves significant time on every case. Reports are recognized by major insurance carriers, and we have the ability to reopen underpaid claims up to two years old.
Report Options and Pricing
We offer a tiered suite of reports designed to meet the needs of individual policyholders and legal professionals. Each report is delivered with a carrier demand letter, pre-addressed to the at-fault carrier, to streamline the negotiation process.
| Report Type | Best For | Key Features | Price |
|---|---|---|---|
| Silver Report | Quick Market Value Check | Instant results, no card required, basic value range | Free |
| Gold Report | Standard Diminished Value | Inherent DV analysis, comparable sales grid, demand letter | $199.95 |
| Platinum Report | Complex Disputes | Full reparability analysis, loss of use, ACV, expert support | Contact for Quote |
The Silver Report provides a free, instant check of your car's real market value. The Gold Report is our most popular option for inherent diminished value, offering a comprehensive analysis backed by a $600 money-back guarantee. For complex cases involving total loss negotiations or disputed valuations, the Platinum Report provides the deepest level of support.
Key Takeaways
- Diminished value is real: Your vehicle loses value after an accident, even with perfect repairs.
- Insurers often underpay: Carrier algorithms frequently ignore market realities, leaving money on the table.
- Verified data is key: Real comparable sales provide the most defensible evidence for your claim.
- 50-state coverage: Diminished value recovery is available in all 50 states, including Texas, California, and New York.
- Law firm support: Bulk solutions are available for PI firms to streamline property damage claims.
- Money-back guarantee: Our Gold Report comes with a $600 guarantee if the recovery amount is less than the report cost.
- Fast delivery: Reports are typically delivered within 48 hours, with some instant options available.
Frequently Asked Questions
What is the difference between inherent and repair-related diminished value?
Inherent diminished value is the loss in value due solely to the accident history on the vehicle's record. Repair-related diminished value occurs when the repairs themselves were not performed correctly or used inferior parts, further reducing the vehicle's worth.
How much does a diminished value report cost?
Our Gold Report, which covers inherent diminished value, costs $199.95. The Silver Report is free for a quick market value check. Platinum Reports for complex disputes are priced based on the specific requirements of the case.
Can I claim diminished value if I have full coverage?
Yes. Diminished value is a separate claim from collision or comprehensive coverage. It addresses the loss in market value, not the cost of repairs. You can pursue this claim against the at-fault party's insurance carrier.
How long do I have to file a diminished value claim?
Time limits vary by state, but we have the ability to reopen underpaid claims up to two years old in many jurisdictions. It is best to act quickly to preserve evidence and ensure accurate comparable sales data.
What is the WHO OWES WHAT Portal?
The WHO OWES WHAT Portal is a centralized platform for law firms to manage property damage work. It allows teams to handle dozens or hundreds of files efficiently, simplifying communication and improving consistency across all cases.
Does Vehicle Value Analysis operate in all 50 states?
Yes, diminished value coverage is available in all 50 states. We provide state-specific guides and valuation support tailored to local market conditions and legal requirements.
What is the $600 money-back guarantee?
If the diminished value amount we calculate and help you recover is less than the cost of the Gold Report ($199.95), we will refund the difference up to $600. This ensures you only pay for value that exceeds the report cost.
Start Your Recovery
Do not let your insurance carrier undervalue your vehicle. Get your free Silver Report today to see your car's real market value, or start your Gold Report to recover your post-repair loss. Our team is ready to help you navigate the complexities of diminished value claims with confidence and precision.
See Your True Market Value and take the first step toward full indemnification.